

Wealth Management and Digital Assets, moving from experimentation to full-scale adoption
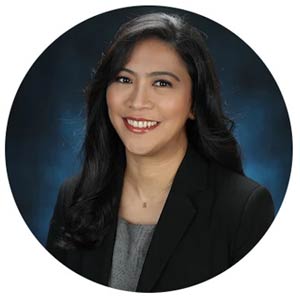
Ann-Marie O'malley, Executive Director, Head of Platform Services, Global Internal Consulting, UBS
Ann-Marie O'malley, Executive Director, Head of Platform Services, Global Internal Consulting, UBS
The future of wealth management is looking bright. Technology is playing an increasingly important role in the way wealth is managed, with automated systems and data analytics being used to make more informed decisions. Additionally, artificial intelligence and machine learning are becoming more commonplace, allowing for better risk management and more efficient portfolio management. However, there is a limit to how much artificial intelligence and optimized analytics can accomplish from a client's perspective.
The rise of digital banking and the increasing demand for digital assets will continue to shape the future of wealth management in the coming years.
In response, Financial institutions have been experimenting with leveraging digital assets to create new products and services, such as digital asset-backed loans and investments. Recently we have seen the launch of tokenized bonds as an alternative form of investment. These products offer investors a new way to diversify their portfolios and gain exposure to the digital asset market.
As the demand for digital assets increases and the experiments turn to pilots with the intention to go to scale, the need to integrate them into the financial services ecosystem is becoming increasingly apparent. Financial services organisations will be unable to capitalize on the full value proposition. The benefits will be limited to efficiency gains from digitizing discreet components of the process within the bank's own systems vs being able to tap into new revenue streams such as secondary liquidity markets. Ultimately limiting their ability to support their client's objectives and deliver agility into their investment portfolio. Innovation will become stifled if it cannot bridge from traditional products to modern financial products.
The challenges in moving from experimentation are known. The major headwinds are technology and Regulatory & Compliance in nature:
The ability to scale to high volumes of transactions is both a technology constraint of the inherent blockchain protocol and an operational challenge as banks are building new modern products on new evolving technology and integrating with traditional operational solutions.
Regulatory & Compliance – As the new asset classes emerge, the regulatory and tax environment is constantly evolving, making keeping up with the requirements a continual challenge to even the most agile of banks. To put it simply, there is no bridge from traditional compliance to new market models and product compliance.
Within those two categories, there are sub-sets: Corporate Culture – or shall we just use the single word "risk."
Investment case – Especially given the competing priorities of digital client-facing solutions and modernization of core banking technology.
Security and Privacy - in the context of peer-to-peer transactions, grappling with the exposure of client data is a huge deterrent.
Employee understanding – Enablement of key banking personnel who have to champion these new products.
Legacy Technology debt – Digital assets sit on modern tech, and modern tech needs to integrate with legacy technology. Depending on how mature the banks' journey to the cloud is, the size of the challenge will vary.
Use case definition - Difficulty identifying valid use cases that speak to the banks and clients' combined objectives; this is balancing out the need for the bank to see a return on the investment in a new asset class and the objective of the client to gain access to innovative investment scenarios. There is no one size fits all answer to these challenges, the big consulting firms will all provide very valuable opinions, but they are just that. This is not a cookie-cutter problem to solve as each bank's digital fingerprint will be different, and each bank will have different strategies by market and line of business.
Regardless, the answer very clearly is not to "do nothing." At some point, because there is a continued concerted effort from intelligent technologists who will not rest, the technology constraints on scaling will be resolved. In regions such as Asia Pacific, where the volume of transactions is a problem that has to be addressed digitally, the local regulatory teams are helping banks to experiment because the region's growth is intrinsically linked with the scaling of trade digitally.
The Rise of Digital Banking and the Increasing Demand for Digital Assets will Continue to Shape The Future of Wealth Management in the Coming Years
When the two major headwinds meet and eventually the pathway forward is visibly less turbulent, only the organisations experimenting "in earnest" with pilots on the verge of going to scale will be in the pole position to accelerate. Fast followers will be able to make good progress by looking at their core strengths, such as custody as a service and by ensuring the strength of their corporate branding is retained as it moves from traditional to modern products. Branding can help because clients who want to evolve their portfolio to new digital asset classes will always trust the iconic brands provided they have got the solutions to work with.
Investing in use cases that start with "do what you do today but do it better" will help the bank make progress and address some of the challenges listed above whilst allowing it enough time to observe the outcomes and progress iteratively.
Finally, investing in carefully curated use cases that address efficiency gains and provide valuable insights into the scaling challenge from both a technology and operational perspective should be prioritized. Strategies incorporating the modernisation of banking platforms alongside these experiments will put the bank in a very good position to accelerate when the chequered flag is lifted.

